China Daily Energy & Industrial Intelligence Brief
📊 Key Market Indicators
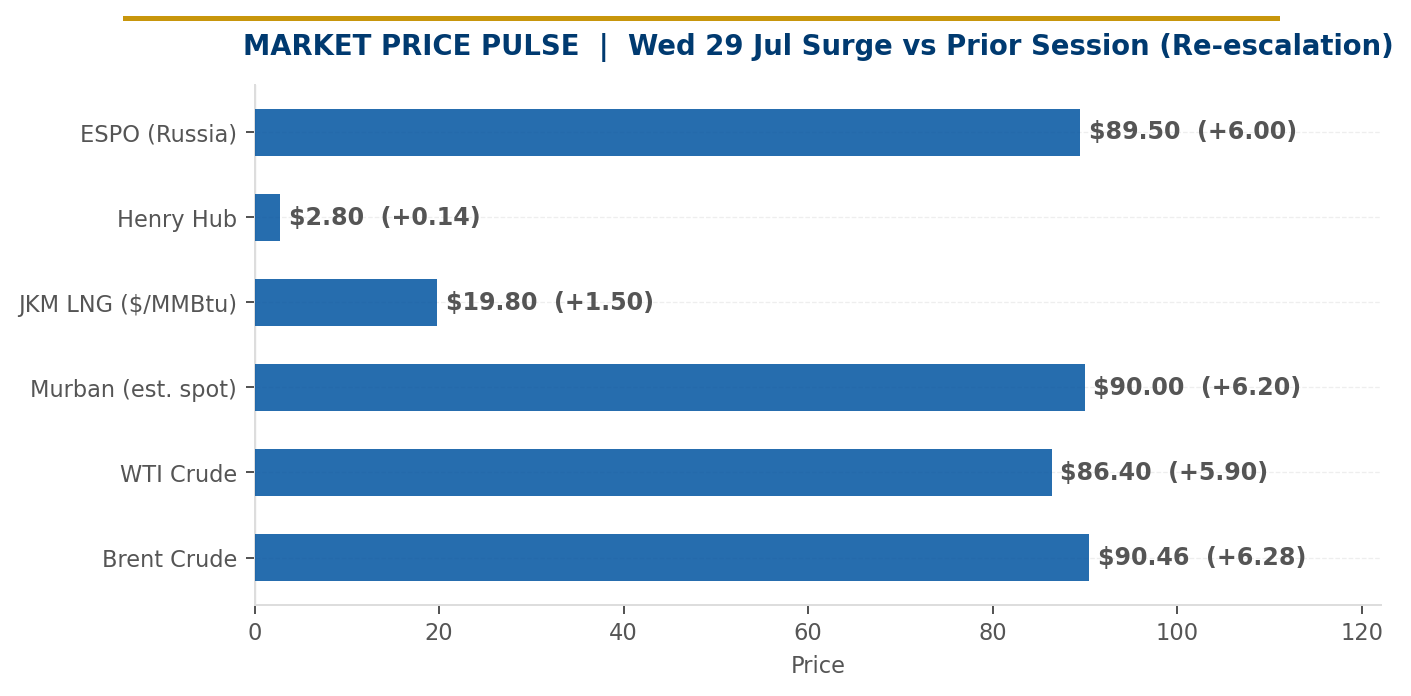
📈 Market Price Pulse
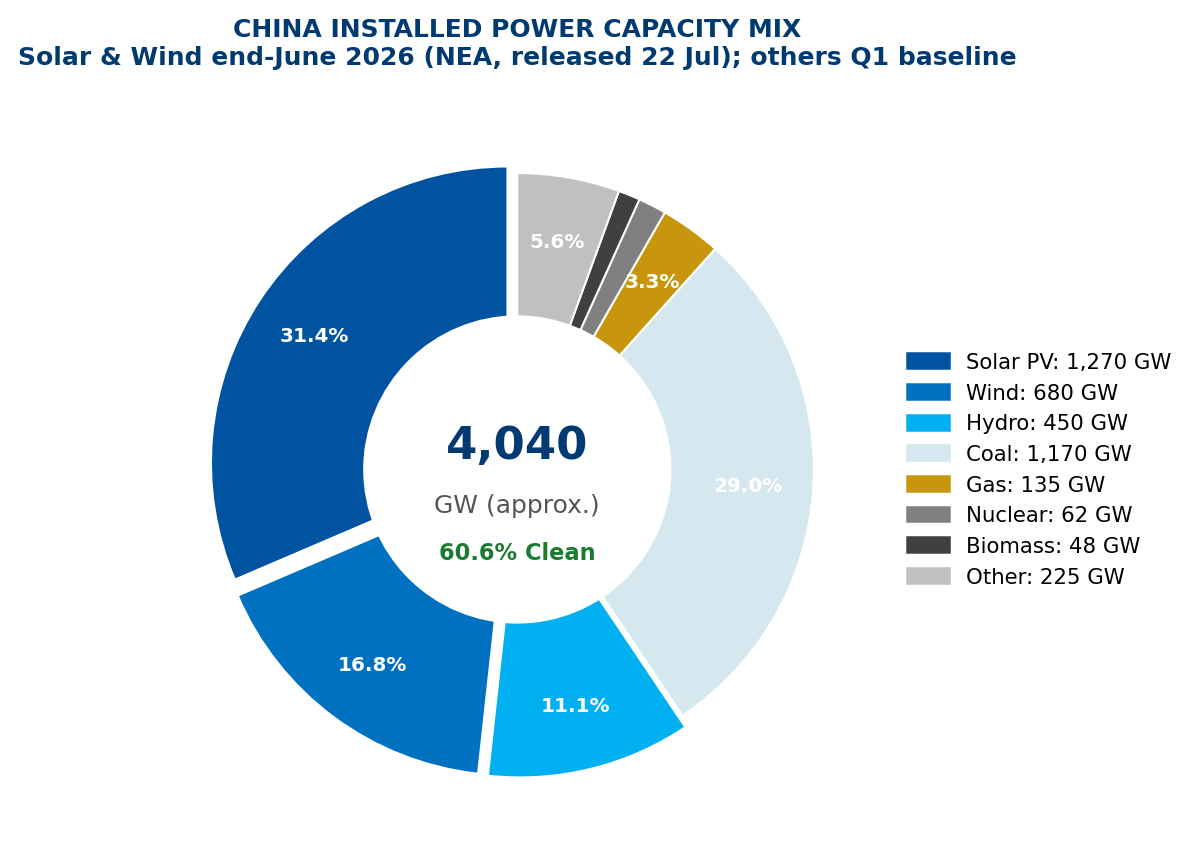
⚡ China Energy Mix
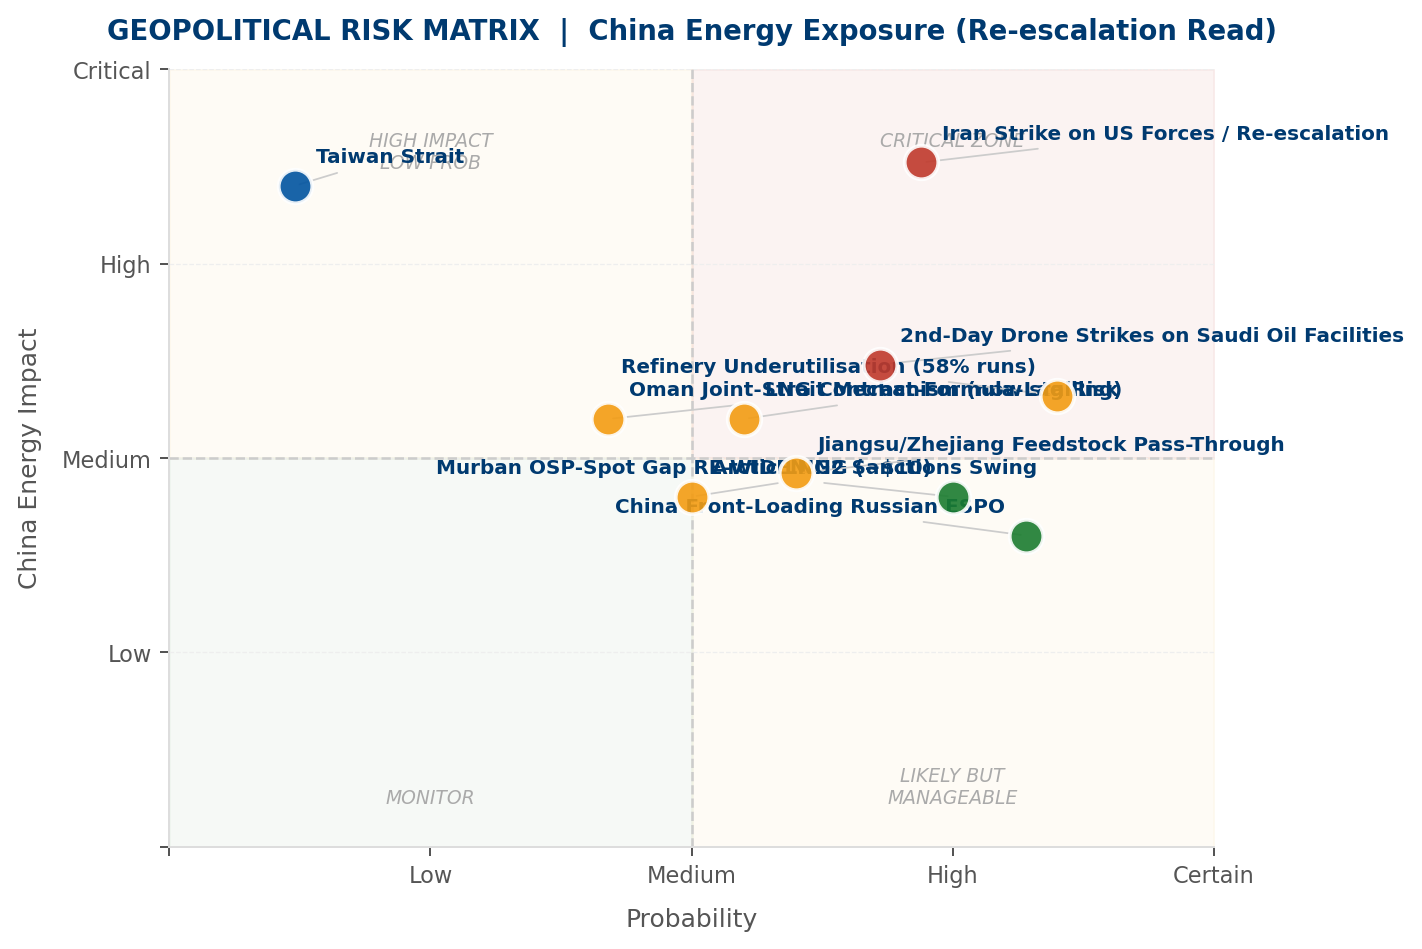
🌍 Geopolitical Risk Matrix
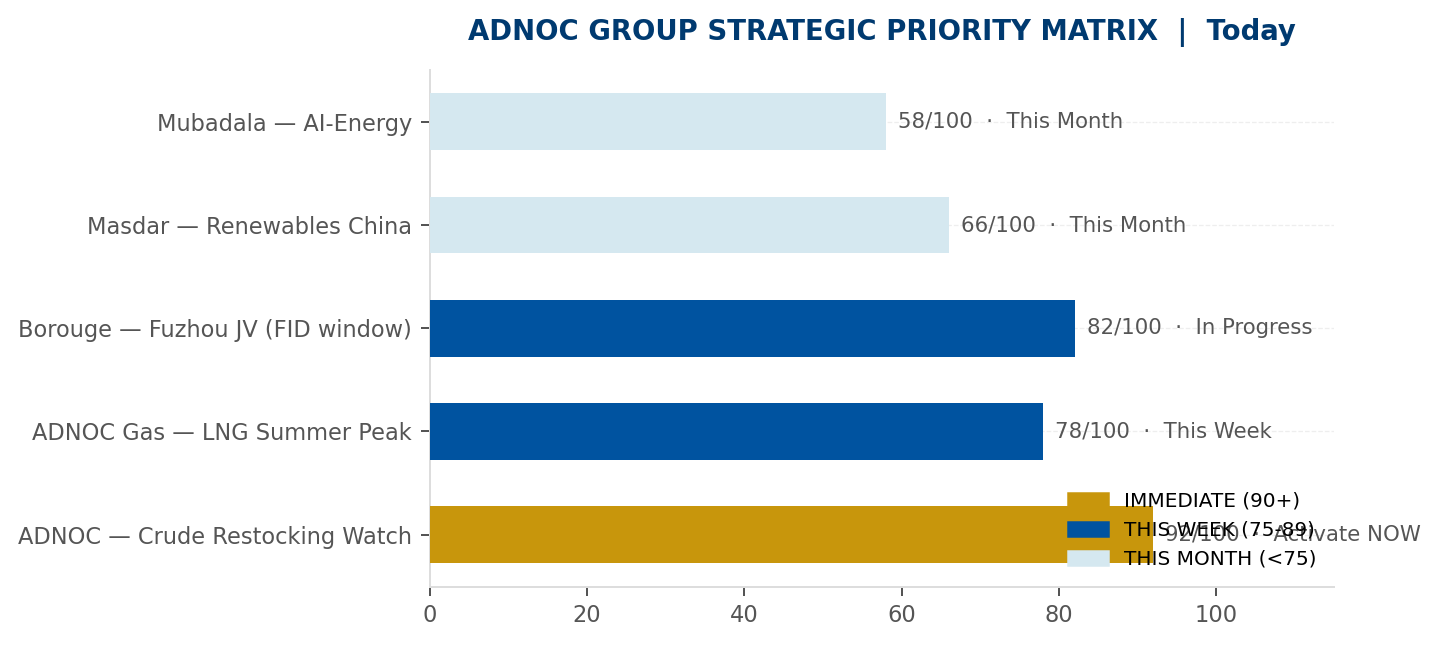
🏢 ADNOC Group Priority Urgency
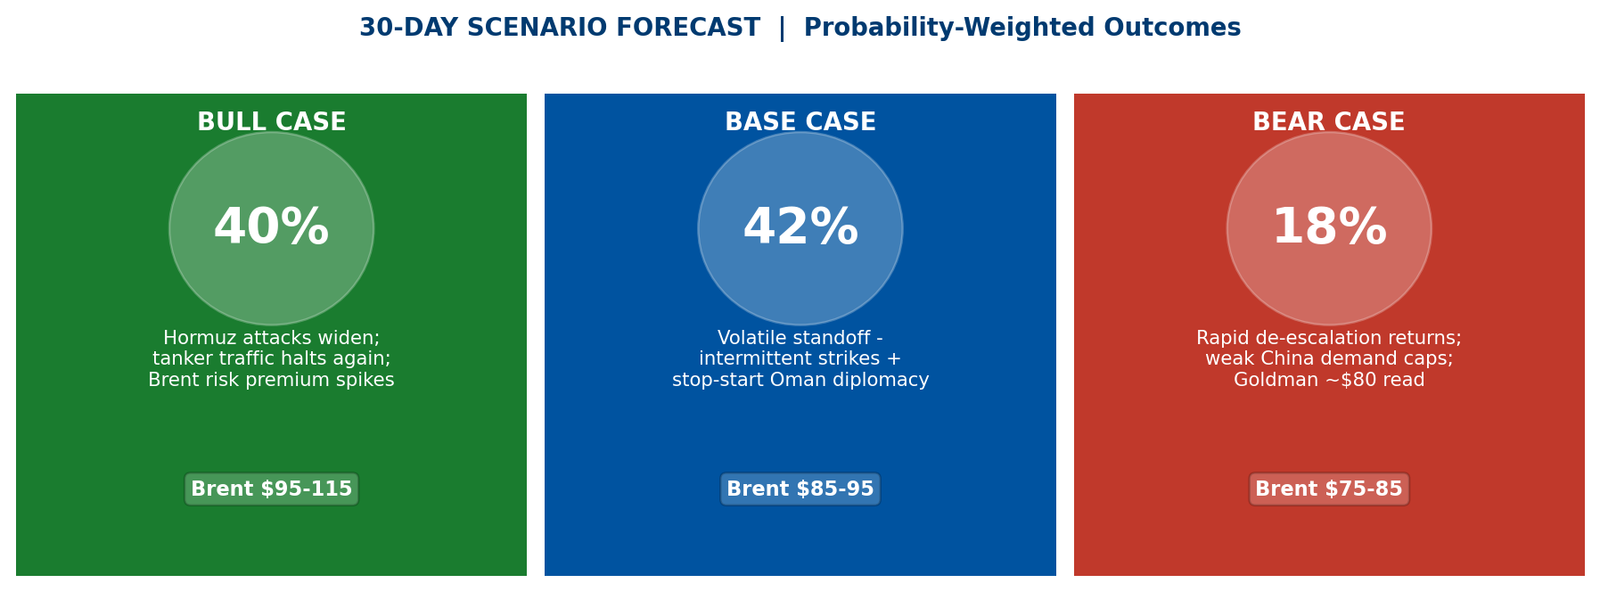
🔮 30-Day Scenario Forecast
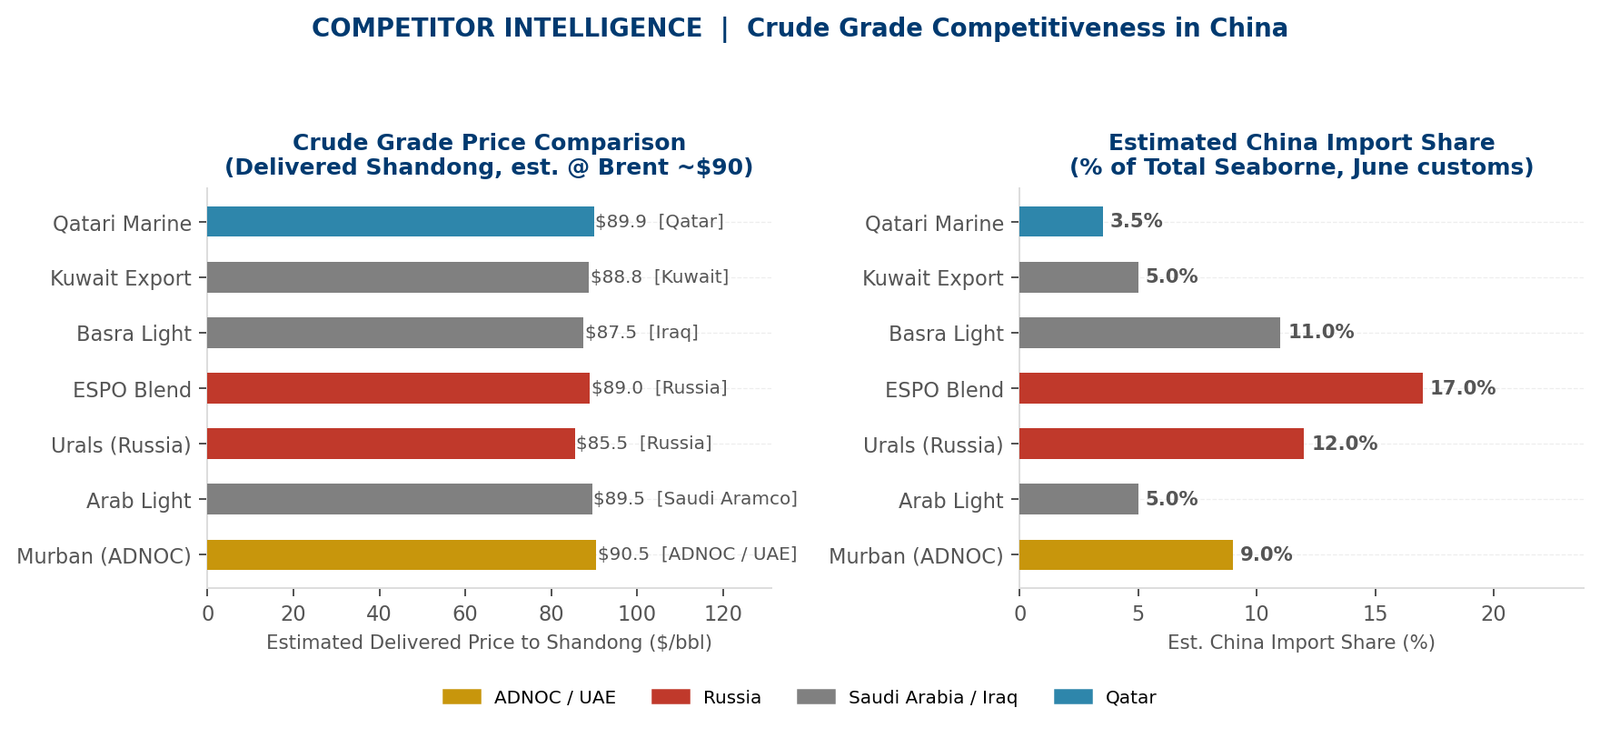
🔍 Competitor Intelligence
📋 Full Intelligence Report
ADNOC CHINA DAILY ENERGY & INDUSTRIAL INTELLIGENCE BRIEF
29 JULY 2026 — WEDNESDAY
Executive Summary
Brent fell to approximately $83/bbl at Tuesday’s close (28 July), down about 6.2% to a one-week low and a third consecutive losing session, as the US–Iran military pause held and Iran’s foreign minister opened separate Hormuz talks with his Saudi and Omani counterparts. (Source: tradingeconomics.com)
Oman has proposed a joint regional mechanism to manage the Strait with voluntary Iranian transit fees, reportedly backed by Gulf states; Trump described “good talks” with Tehran while warning strikes could resume. Risk is not gone — Saudi Arabia intercepted drones targeting oil facilities and Yemen’s Houthis claimed an attack on the kingdom’s East-West pipeline. (Source: tradingeconomics.com)
The commercial consequence for ADNOC is the near-closure of the Murban OSP-spot gap. The fixed August Murban OSP of $80.01/bbl (−21.2% vs July) now sits only ~$3/bbl below spot, versus the ~$16.8/bbl windfall estimated on 28 July — the August fixed-price advantage for Chinese buyers has largely evaporated. The September OSP is not yet published; a circulating “$83.80 September” figure again fails source-date verification (a 2024 article) and is excluded. (Source: economymiddleeast.com)
China’s demand backdrop stays historically weak: June crude imports −41.3% YoY to 29.27 MT (lowest since Oct 2016) and refinery throughput −17.7% YoY to 51.24 MT (lowest since March 2020, ~58% runs), with a ~940 kb/d inventory draw. Russia held ~29% of June imports; Saudi Arabia collapsed to ~5% (−57% YoY). (Source: hydrocarbonprocessing.com)
Today’s Wednesday rotation covers Guangdong — LNG terminals, Borouge polymer demand, and the BYD/GAC/XPeng EV cluster; its high thermal share and energy-import dependence give it the top Gas-to-Power Pass-Through score (5/5).
Gas & LNG Command Center — Top Finding
The gas signal stays two-sided: China restarted LNG re-exports on sufficient summer supply and a stronger JKM (July avg ~$18.78/MMBtu; Sept strip >$21), redirecting surplus cargoes overseas rather than booking domestic losses of ~Yuan 100–400/tonne. Soft domestic gas demand cuts against new China offtake and can leave ADNOC Gas’s oil-indexed China contracts priced above a falling spot. (Source: cyprusshippingnews.com)
Key Market Indicators
| Market Marker | Latest | Signal / Trend |
|---|---|---|
| Brent Crude | ~$83/bbl | Tue 28 Jul close, −6.2%; one-week low, 3rd straight down session on de-escalation |
| WTI / Urals | ~$78 / $76.94 | Both sharply lower as US–Iran pause and Oman Hormuz mechanism ease supply fears |
| ADNOC Aug Murban OSP | $80.01/bbl | Fixed (−21.2% vs Jul); September OSP not published; “$83.80” is a 2024 figure, excluded |
| Murban OSP–Spot Gap | ~−$3/bbl | Collapsed from ~−$16.8 (28 Jul) as spot fell to the OSP; windfall closing |
| JKM LNG (NE Asia spot) | ~$18.3/MMBtu | Jul avg $18.78; Sept strip >$21; China now a NET re-exporter of surplus |
| China June Refinery Throughput | 51.24 MT | −17.7% YoY, lowest since Mar 2020; ~58% run rate; ~940 kb/d inventory draw |
| China Renewables (end-June) | 4,040 GW total | Solar 1,270 GW (+15.8%), Wind 680 GW (+18.5%); H1 solar adds −66% YoY |
Highlights
Provincial Deep Dive — Guangdong
Guangdong is China’s gas-fired-power and LNG-import heartland and the most fuel-price-sensitive grid in the country. Guangdong Energy Group’s 4 MTPA Huizhou regasification terminal and the Nansha peak-shaving station carry the province’s gas peaking load; because the grid runs a high thermal share with high energy-import dependence, international fuel prices transmit to power prices more directly than anywhere else — the basis for its 5/5 Gas-to-Power Pass-Through score. After averaging RMB376/MWh in the week to 4 July, Guangdong spot power is expected to break the prior RMB0.6/kWh peak in the July–August load window. The province also anchors China’s EV cluster (BYD/GAC/XPeng), with >3 million EV chargers planned by 2027 — Borouge’s most attractive China demand vector for lightweighting polyolefins and cable compounds. (Source: fxbaogao.com; cnevpost.com)
Note — Source-Date Verification This Run (Step 1B)
Today’s Brent/WTI/Urals levels were confirmed against a Trading Economics reading explicitly stamped 28 July 2026 (Brent 82.88–83.20, −6.2%) rather than reused from the prior report’s higher ~$96.78 intraday figure, which belonged to an earlier re-escalation phase. The “$83.80 September Murban OSP” figure was again rejected as a 2024 article; September OSP is presented as “not yet published.” June China customs/NBS data carry explicit 2026 dates from the 15 July release.