China Daily Energy & Industrial Intelligence Brief
📊 Key Market Indicators
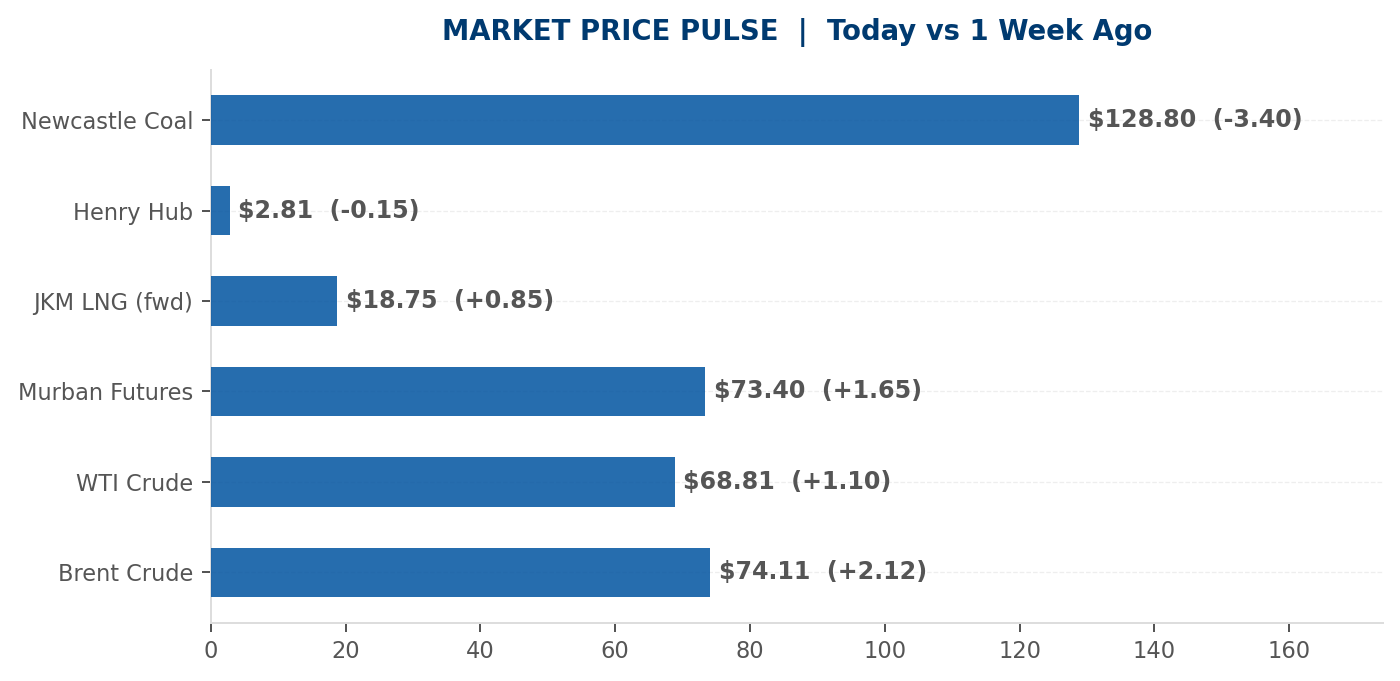
📈 Market Price Pulse
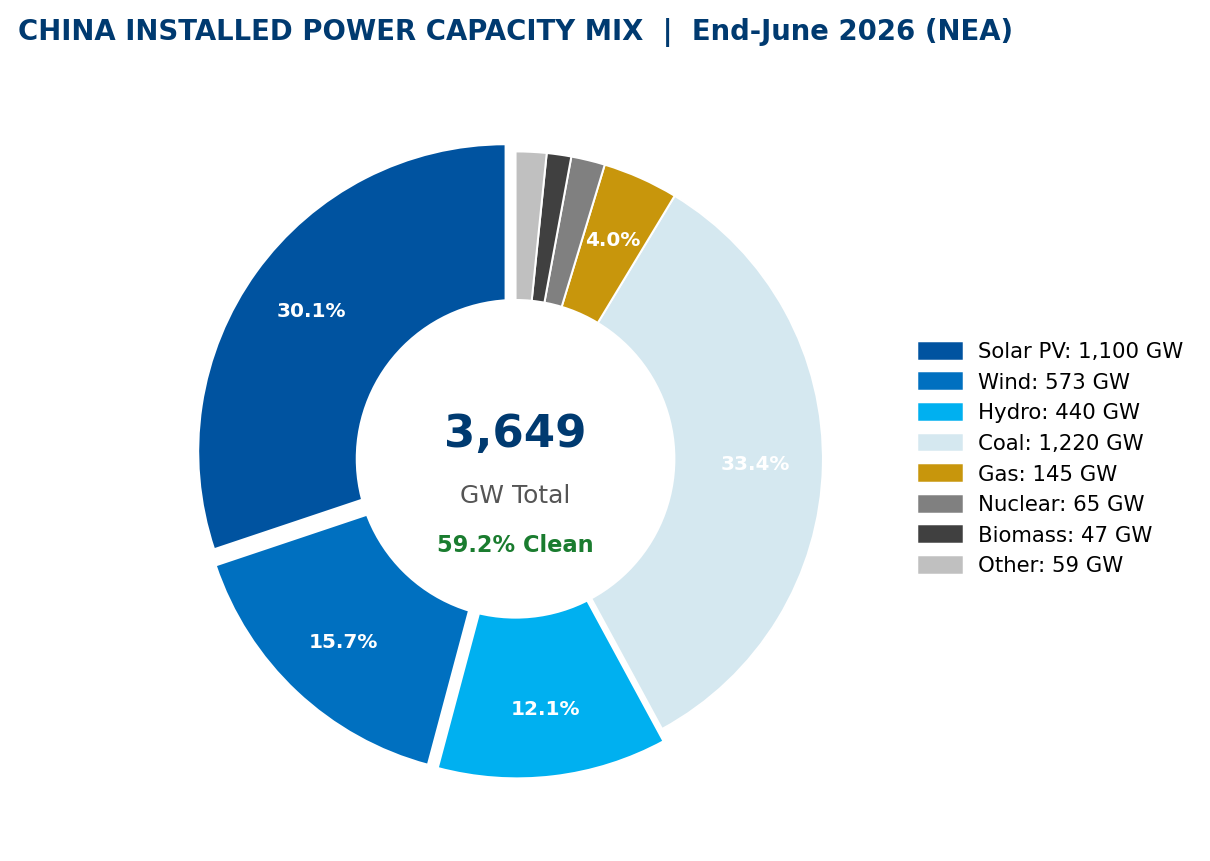
⚡ China Energy Mix
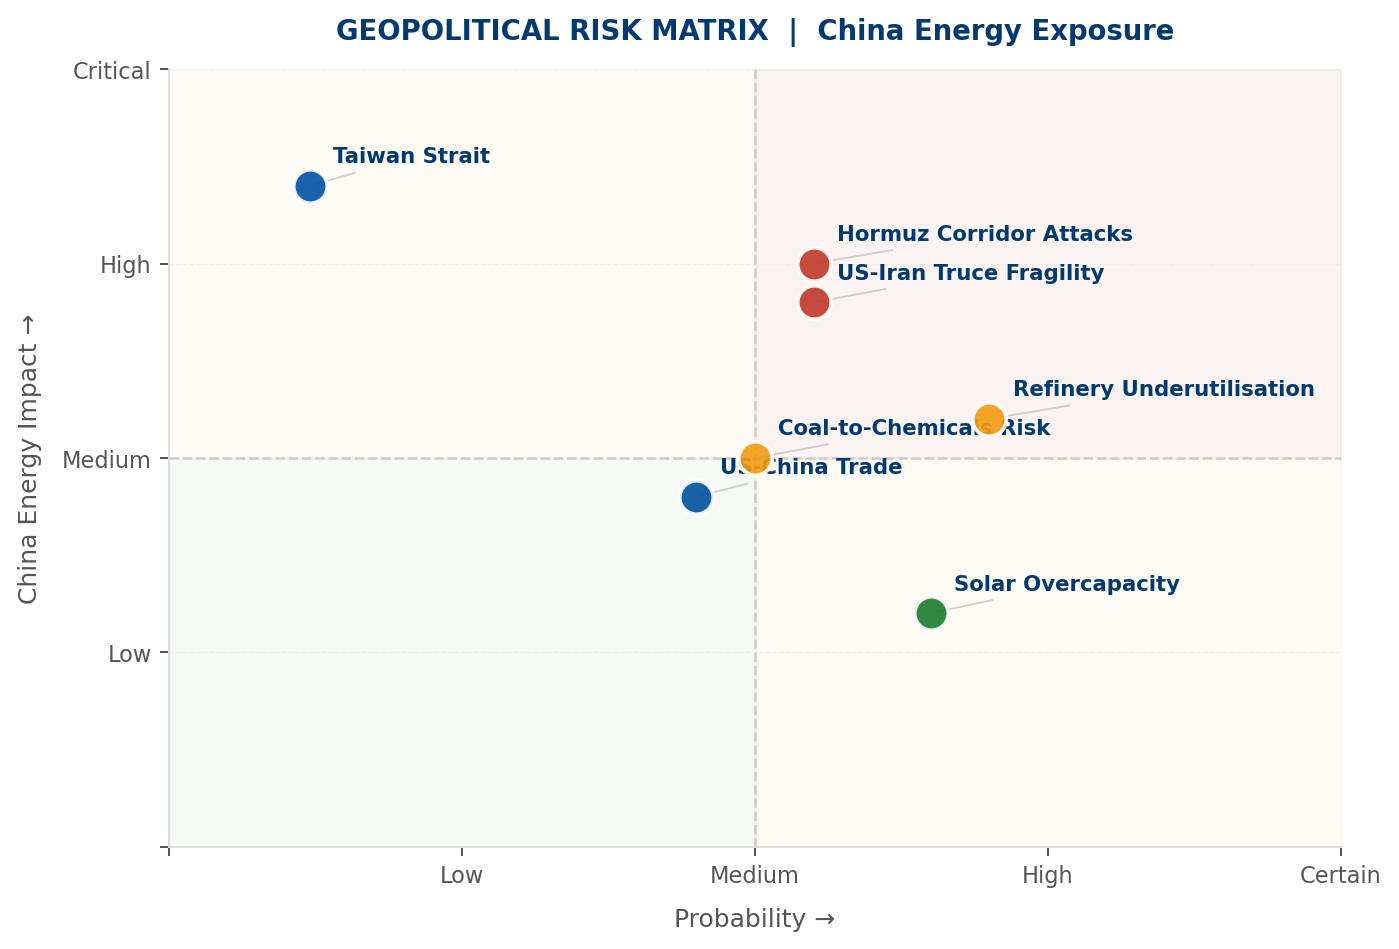
🌍 Geopolitical Risk Matrix
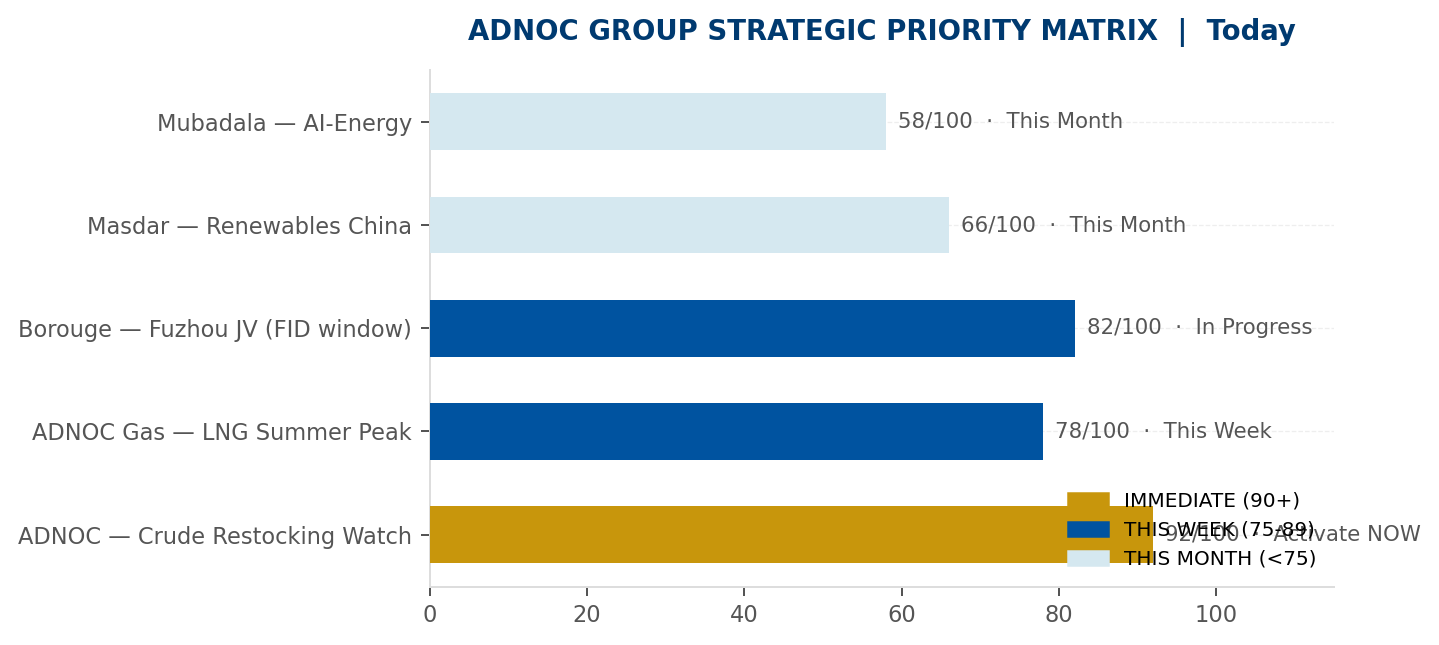
🏢 ADNOC Group Priority Urgency
🔮 30-Day Scenario Forecast
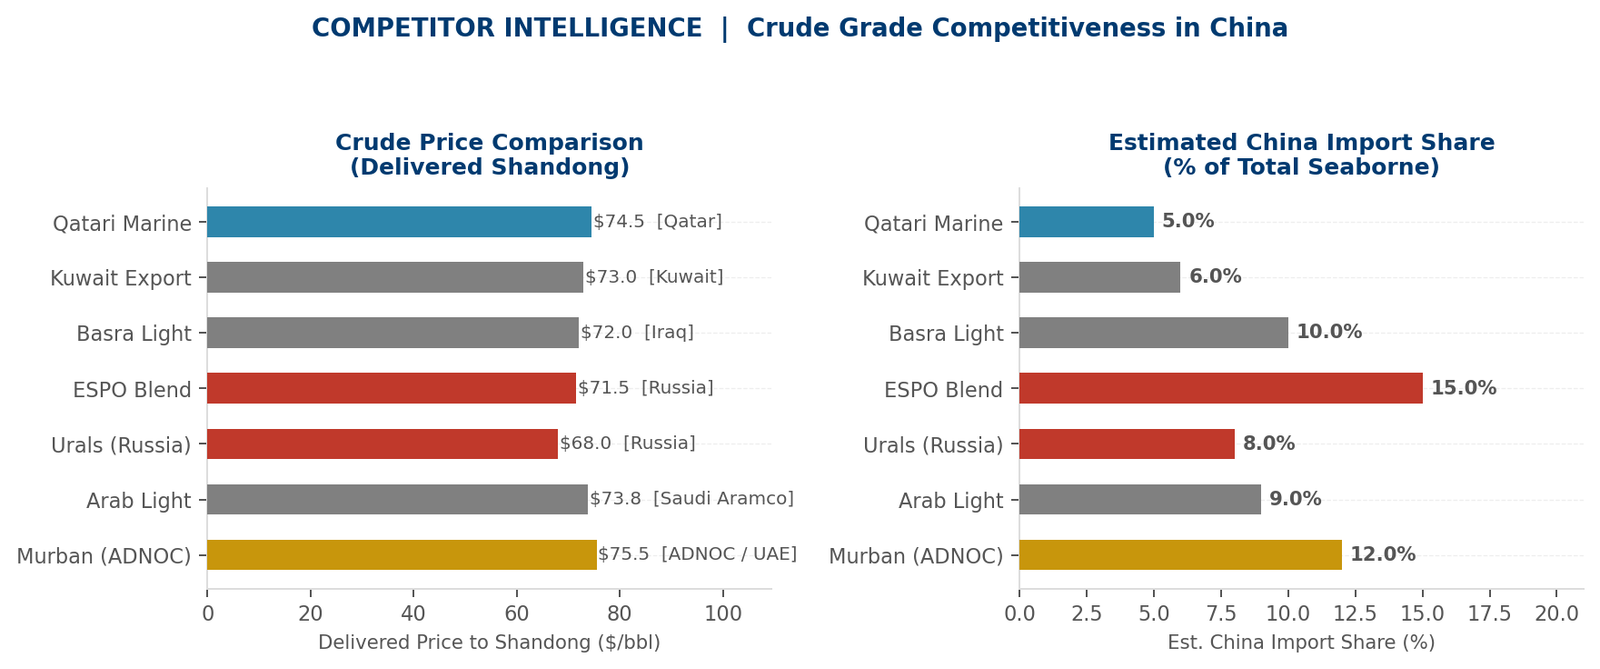
🔍 Competitor Intelligence
📋 Full Intelligence Report
ADNOC China Daily Energy & Industrial Intelligence Brief
POLICY SENTIMENT SCORE: 6.5/10 — NEUTRAL-HAWKISH (binding NDRC/NEA industrial green-power-consumption mandate took full effect 1 Aug; layered on the 23 Jul Renewable 15th FYP; “加快/大力推进” framing tempered by “稳步/可靠替代” language and cautious pricing reform)
Executive Summary
The Hormuz whipsaw remains the base regime. A brief mid-week recovery in Strait tanker traffic faded once more; ship-tracking firms recorded transits collapsing back toward zero after renewed US–Iran friction, and President Trump reimposed a blockade on Iranian-flagged vessels while demanding a 20% cargo-value transit fee from other ships. Iran continues to subject shipping to its own conditions — pre-approved routes, voyage-information sharing, transit fees. The read is an unresolved, fee-encumbered standoff, not a durable pause. (Source: NBC News; CNBC)
Brent held near $88 into the 1 August close, up more than 20% on the month; WTI ~$84.6. Goldman Sachs expects oil to hold most of its gains through July–August while maintaining a Q4 2026 Brent forecast of ~$80 if tensions ease, and flagging upside above $120 if Hormuz stays disrupted. For ADNOC the fixed $80.01 August Murban OSP now sits ~$8/bbl below spot — narrowed from ~$9.6 a session earlier — so the windfall is live but decaying as spot drifts toward the OSP. The September OSP is due the first business days of August and is unpublished; the recurring “$83.80 September” figure again traces to a 2024 article and is excluded. Separately, ADNOC confirmed on 31 July that from November 2026 Murban OSPs will be set off prompt-month Platts Dubai plus an ADNOC differential, replacing the IFAD method. (Source: Investing.com; ADNOC)
China’s underlying demand stays historically weak — June refinery throughput 51.24 MT (-17.7% YoY, ~12.47 Mb/d, ~58% runs, sharpest YoY drop on record, ~1 Mb/d implied stock draw) — but July seaborne imports are set to rebound to ~7.8 Mb/d from June’s 6.2 Mb/d decade low, with Saudi shipments more than doubling, UAE volumes surging more than tenfold off a low base, and Russian inflows up ~10% — a scramble to refill war-lost barrels, not a demand recovery. (Source: Yahoo Finance / Kpler)
National Overview — Weekly Synthesis
Sunday’s rotation steps back to the national picture, dominated by a structural inflection in China’s power system: H1 2026 renewable generation surpassed 40% of total output for the first time (41.2%) while coal’s share fell below 50% (49.7%), and combined wind+solar capacity reached ~1,950 GW end-June (+16.8% YoY; solar 1.27 TW +15.8%, wind 680 GW +18.5%) within a 4.04 TW total base. Beijing’s binding industrial green-power-consumption mandate — live from 1 August — converts that supply into obligatory downstream demand across steel, cement, chemicals, aluminium and data centres, shifting the transition from building clean power to forcing its use. Cross-province, this compresses gas-to-power pass-through everywhere over time — most in high-elasticity coastal provinces (Guangdong, Jiangsu/Zhejiang), least in already-renewable interior grids (Xinjiang) — a slow, policy-enforced erosion of the China gas-demand growth thesis and an opening for Masdar and XRG green-molecule positioning. (Source: TechNode; Argus)
Gas & LNG Command Center — Top Finding
JKM firmed to ~$21.4/MMBtu on 31 July (from the high-$17s early July) as the Hormuz shipment-risk premium and summer demand held (TTF ~€58.3/MWh; Henry Hub ~$2.95) — but the signal stays two-sided: China remains a net LNG re-exporter on soft domestic demand, so the firmer spot improves ADNOC Gas’s reload-arbitrage while a still-firm Brent near $88 keeps its ~2.28 MTPA oil-indexed China contracts re-rated UP into a market soft enough to invite buyer renegotiation. The $21.4 print is a single-index reading, flagged as such. Formula discipline, not spot-chasing, remains the call. (Source: LNG Price Index; Cyprus Shipping News)
Key Market Indicators
| Marker | Latest | Signal |
|---|---|---|
| Brent Crude | ~$88.2/bbl | Held ~$88 into 1 Aug close, +20%+ on the month; Hormuz whipsaw persists, blockade re-imposed |
| WTI Crude | ~$84.6/bbl | Held ~$84.6 as the Middle East risk premium persisted |
| Aug Murban OSP | $80.01/bbl | Fixed (-21.2% vs Jul $101.48); Sept OSP due early Aug, not yet published; “$83.80” is a 2024 figure |
| Murban OSP-Spot Gap | ~-$8/bbl | Narrowing as spot eases toward the fixed $80.01 OSP; windfall live but decaying |
| JKM LNG (NE Asia) | ~$21.4/MMBtu | Firmed to low-$20s on 31 Jul on Hormuz risk + summer demand; China still net re-exporter |
| China Jun Throughput | 51.24 MT | -17.7% YoY, sharpest on record; ~12.47 Mb/d, ~58% runs; ~1 Mb/d stock draw |
| China Jul Seaborne Imports (est.) | ~7.8 Mb/d | Rebounding from Jun’s 6.2 Mb/d decade low; Saudi >2x, UAE >10x, Russia +10% (Kpler) |
| H1 Renewable Generation | 41.2% | First time >40% of power mix; coal share 49.7%, below 50% for the first time |
| Wind+Solar Capacity (end-Jun) | ~1,950 GW | +16.8% YoY; solar 1.27 TW (+15.8%), wind 680 GW (+18.5%); total capacity 4.04 TW |
The full 20-section formatted Word document (with all 7 embedded infographic charts) is saved locally in the ADNOC news folder and uploaded as a summary to the Google Drive “ADNOC Energy Briefing / Daily” folder. Classification: ADNOC Internal — Not for external distribution. September Murban OSP due early August, withheld pending source-date verification.